
Since inception, OCIC has delivered strong results across a variety of market environments, reflecting our disciplined underwriting approach and defensively constructed portfolio. We believe these foundational characteristics position the fund to pursue attractive risk-adjusted returns over time. The fund has delivered a 9.3%* ITD Class I return.1
Direct lending has the ability to weather market volatility and can continue to play an important part of overall portfolio allocations
OCIC is well positioned to continue performing as designed, seeking current income with a focus on risk management.
We believe that market conditions have shifted in direct lending’s favor. In September 2026, the Federal Reserve increased the federal funds rate by 25 basis points, with interest rate markets forecasting up to two further 25 basis point hikes through the end of 1Q’272. As a result, higher base rates should support coupon income across OCIC's predominately floating-rate portfolio. In our view, direct lending spreads have also widened3,4, driven largely by macroeconomic and geopolitical uncertainty. When coupled together, these dynamics may improve all-in yields on new originations and potentially create an attractive environment for deployment. Finally, the fundamental starting point is strong, with defaults remaining contained across the direct lending market5,6.
| 4Q 2025 | Current | Overall Trend | |
|---|---|---|---|
|
Rates |
~50 bps7 Down |
~50 bps2 Up |
▲ |
|
Spreads |
~450-500bps |
~500-550bps |
▲ |
|
Defaults |
0.7% |
0.9% |
▬ |
OCIC continues to deliver predictable income generation and strong credit performance during the current environment including through recent volatility. Our performance reflects careful and deliberate asset selection and portfolio management. The fund’s focus on investments at the top of the capital structure in large, sponsor-backed businesses supported by substantial equity cushions, provides meaningful downside protection. At the same time, the fund’s scale supports broad diversification and limits concentration across individual companies and industries.
As of September 30, 2026. Past performance is not indicative of future results. All investments are subject to risk, including the loss of the principal amount invested. This information is being provided for illustrative/informational purposes only, not indicative of actual client results. References to “downside protection” or similar language are not guarantees against loss of investment capital or value. The views expressed are Blue Owl’s and subject to change without notice as market and other conditions change.
Our strategy remains consistent and our year-to-date credit performance has been strong. We have not seen any new issuers on non-accruals this year in the OCIC portfolio, and the fund's non-accruals stand at just 0.2% of fair value10 – comfortably below the upper middle market direct lending average of 0.9%6. ~95% of the portfolio is performing in line or ahead of expectations over the past three years11 and the underperforming names reflect a consistent and well understood population. Finally, in an environment with modestly higher base rates and the potential for additional hikes, interest coverage starts from a firm position at 2.1x today12.
OCIC continues to deliver strong income-driven returns, supported by a defensively constructed and broadly diversified portfolio. Through September 2026, OCIC (Class I) has returned 5.2% year-to-date and was the best-performing scaled non-traded BDC within the peer group through September 202613.
When looking at traditional public credit, OCIC (Class I) has generated a 9.3% annualized total return, outperforming leveraged loans and high yield bonds by nearly 330 and 540 basis points, respectively.14 We view this sustained outperformance as underscoring the potential value of direct lending relative to traditional public credit indices.
Robust performance remains supported by strong credit fundamentals, including a non-accrual rate of 0.2% at fair value. We believe this combination of performance, current income and underlying credit quality is important as dispersion across the asset class grows and manager selection becomes increasingly critical.
OCIC has a strong valuation policy that has been consistent since inception and is monitored by the Valuation Committee of the OCIC board. Each of the positions in the OCIC portfolio are valued monthly by a 3rd party valuation agent who determines a point estimate of fair value for each position taking into account all available information. Our valuation reflects fundamental credit performance and market factors including market spreads and trading performance for comparable companies. Additionally, the par value, cost basis, and fair value for every position in OCIC is publicly available through our quarterly filings. In 2Q’26, the fair value of OCIC’s debt investments as a percentage of par was 97.3%15, compared to 98.4% in 4Q’2516.
The year-to-date decline in NAV has been driven primarily by broader market factors, including wider credit spreads and weaker public loan prices. Importantly, the decline in NAV is not reflective of broad-based deterioration in the portfolio.
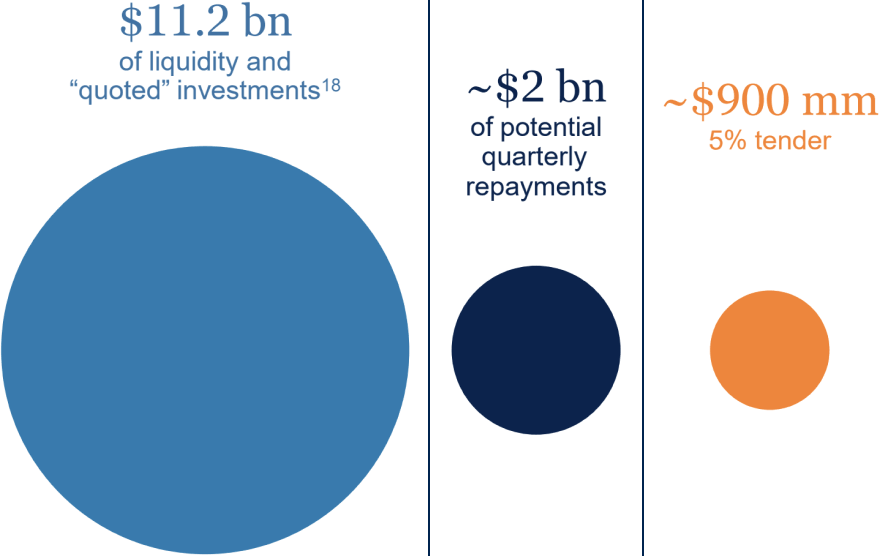
OCIC’s 5% quarterly repurchase limit was built to balance shareholder liquidity against capital preservation, matching asset and liabilities so the fund is not forced to sell private loans to meet redemptions. The result is continued access to the return premium private credit offers, while leaving OCIC well capitalized for deployment opportunities ahead.
OCIC's liquidity profile represents more than 12x the dollar amount needed for OCIC to meet the typical 5% quarterly repurchase offer. In addition, the portfolio typically sees 6% - 8% of its total investments repay each quarter, which amounts to ~$2 billion of potential incremental liquidity.
OCIC available liquidity and potential repayments vs maximum tender17

Despite the volatile market environment in 2026, OCIC continues to deliver attractive returns which are mainly driven by income, and its credit fundamentals remain resilient. Looking ahead, our deliberate credit selection, combined with prudent portfolio management and liquidity management, can potentially position us well to benefit from an evolving direct lending backdrop.
Your go-to for an owl’s-eye view on what matters most to us in Private Wealth.
Endnotes
| Total Returns | 1-Month | 3-Month | YTD | 1-Year | 3-Year | 5-year | ITD (annualized) |
| Class S (With Max Sales Load) | -2.39% | -0.36% | 0.88% | 2.39% | 7.33% | 7.76% | 7.70% |
| Class S (No Max Sales Load) | 1.03% | 3.13% | 4.41% | 5.98% | 8.57% | 8.51% | 8.38% |
| Class D (With Max Sales Load) | -0.42% | 1.75% | 3.32% | 5.03% | 8.66% | 8.84% | 8.71% |
| Class D (No Max Sales Load) | 1.08% | 3.28% | 4.87% | 6.60% | 9.20% | 9.17% | 9.00% |
| Class I | 1.10% | 3.33% | 5.17% | 6.86% | 9.46% | 9.45% | 9.30% |
OCIC risk factors
An investment in Blue Owl Credit Income Corp. (“OCIC”) is speculative and involves a high degree of risk, including the risk of a substantial loss of investment, as well as substantial fees and costs, all of which can impact an investor's return. The following are some of the risks involved in an investment in OCIC's common shares; however, an investor should carefully consider the fees and expenses and information found in the “Risk Factors” section of the OCIC prospectus before deciding to invest:
Important information
Unless otherwise noted the Report Date referenced herein is as of September 30, 2026.
Past performance is not a guarantee of future results.
Assets Under Management (“AUM”) refers to the assets that we manage and is generally equal to the sum of (i) net asset value (“NAV”); (ii) drawn and undrawn debt; (iii) uncalled capital commitments; (iv) total managed assets for certain Credit and Real Assets products; and (v) par value of collateral for collateralized loan obligations (“CLOs”) and other securitizations.
The material presented is proprietary information regarding Blue Owl Capital Inc. (“Blue Owl”), its affiliates and investment program, funds sponsored by Blue Owl, including the Blue Owl Credit, Real Assets, and GP Strategic Capital Funds (collectively the “Blue Owl Funds”) as well as investment held by the Blue Owl Funds.
An investment in the Fund or other investment vehicle entails a high degree of risk. You should consider all of the risk factors set forth in the "Certain Risk Factors and Actual and Potential Conflicts of Interest" of the PPM or Prospectus, each of which could have an adverse effect on the Fund or other investment vehicle and on the value of Interests.
An investment in the Fund or other investment vehicle is suitable only for sophisticated investors and requires the financial ability and willingness to accept the high risks and lack of liquidity associated with an investment in the Fund or other investment vehicle. Investors in the Fund or other investment vehicle must be prepared to bear such risks for an indefinite period of time. There will be restrictions on transferring interests in the Fund or other investment vehicle, and the investment performance of the Fund or other investment vehicle may be volatile. Investors must be prepared to hold their interests in the Fund or other investment vehicle until its dissolution and should have the financial ability and willingness to accept the risk characteristics of the Fund's or other investment vehicle’s investments.
There can be no assurances or guarantees that the Fund's or other investment vehicles investment objectives will be realized that the Fund's or other investment vehicle investment strategy will prove successful or that investors will not lose all or a portion of their investment in the Fund.
Furthermore, investors should not construe the performance of any predecessor funds or other investment vehicle as providing any assurances or predictive value regarding future performance of the Fund.
The views expressed and, except as otherwise indicated, the information provided are as of the report date and are subject to change, update, revision, verification, and amendment, materially or otherwise, without notice, as market or other conditions change. Since these conditions can change frequently, there can be no assurance that the trends described herein will continue or that any forecasts are accurate. In addition, certain of the statements contained in this material may be statements of future expectations and other forward-looking statements that are based on the current views and assumptions of Blue Owl and involve known and unknown risks and uncertainties (including those discussed below) that could cause actual results, performance, or events to differ materially from those expressed or implied in such statements. These statements may be forward-looking by reason of context or identified by words such as “may, will, should, expects, plans, intends, anticipates, believes, estimates, predicts, potential or continue” and other similar expressions. Neither Blue Owl, its affiliates, nor any of Blue Owl’s or its affiliates' respective advisers, members, directors, officers, partners, agents, representatives or employees or any other person (collectively the “Blue Owl Entities”) is under any obligation to update or keep current the information contained in this document.
This material contains information from third party sources which Blue Owl has not verified. No representation or warranty, express or implied, is given by or on behalf of the Blue Owl Entities as to the accuracy, fairness, correctness or completeness of the information or opinions contained in this material and no liability whatsoever (in negligence or otherwise) is accepted by the Blue Owl Entities for any loss howsoever arising, directly or indirectly, from any use of this material or its contents, or otherwise arising in connection therewith.
All investments are subject to risk, including the loss of the principal amount invested. These risks may include limited operating history, uncertain distributions, inconsistent valuation of the portfolio, changing interest rates, leveraging of assets, reliance on the investment advisor, potential conflicts of interest, payment of substantial fees to the investment advisor and the dealer manager, potential illiquidity, and liquidation at more or less than the original amount invested. Diversification will not guarantee profitability or protection against loss. Performance may be volatile, and the NAV may fluctuate.
Performance Information: Where performance returns have been included in this material, Blue Owl has included herein important information relating to the calculation of these returns as well as other pertinent performance related definitions.
NAV: We intend to sell our shares at a net offering price that we believe reflects the net asset value per share as determined in accordance with the Company’s share pricing policy.
This material is for informational purposes only and is not an offer or a solicitation to sell or subscribe for any fund or other investment vehicle and does not constitute investment, legal, regulatory, business, tax, financial, accounting, or other advice or a recommendation regarding any securities of Blue Owl, of any fund or investment vehicle managed by Blue Owl, or of any other issuer of securities. Only a definitive offering document (i.e.: Prospectus or Private Placement Memorandum or other offering material) can make such an offer. Neither the Securities and Exchange Commission, the Attorney General of the State of New York nor any state securities commission has approved or disapproved of these securities or determined if the Prospectus, Private Placement Memorandum or other offering material is truthful or complete. Any representation to the contrary is a criminal offense. Within the United States and Canada, securities are offered through Blue Owl Securities LLC, member of FINRA/SIPC, as Dealer Manager.
Copyright© Blue Owl Capital Inc. 2026. All rights reserved. This material is proprietary and may not be reproduced, transferred, or distributed in any form without prior written permission from Blue Owl. It is delivered on an “as is” basis without warranty or liability by accepting the information, you agree to abide by all applicable copyright and other laws, as well as any additional copyright notices or restrictions contained in the information.